A CCTV system can fail in several ways. A camera may miss a critical area, a recorder may stop saving footage, remote access may be left exposed, or cabling may damage a client’s property. If a burglary, injury, privacy complaint or financial loss follows, the issue becomes who owes the relevant duty and which policy—if any—responds.
At Global Insurance Solutions (GIS), we treat cctv installer insurance as a risk program, not a catch-all product. The right CCTV installation insurance may involve public liability, professional indemnity, tools, cyber, motor, personal accident or workers compensation cover, depending on the work, contracts and policy wording.
When a CCTV failure becomes an insurance claim?
Imagine a warehouse is burgled after its recorder stopped saving footage. The client blames incorrect configuration and seeks the value of stolen stock.
Elsewhere, remote access exposes recordings, or a technician drills through a water pipe while running cable.
These events may look related, but they raise different questions:
- Was there third-party injury or property damage?
- Did the loss arise from design, advice or programming?
- Is the claim for rectifying defective work or resulting damage?
- Were personal information, subcontractors or height work involved?
No policy pays simply because a system failed. The insurer considers the allegation, cause, timing, exclusions, limits, excess and policy conditions.
Who may pay when the security system fails?
The client may first claim under its property, theft, crime or cyber policy. That insurer could pursue recovery from a party said to have contributed. The installer may need to notify more than one liability insurer, even when responsibility is disputed.
For insurance for cctv installers, the central distinction is often physical damage versus financial loss. Public liability generally addresses third-party injury or property damage; professional indemnity addresses allegations arising from professional advice or services; cyber cover may matter when networks, credentials or recordings are compromised. Multiple policies can be notified, but not every policy will respond.
Public Liability Insurance for CCTV Installers
Public liability insurance for CCTV installers may respond when installation causes third-party injury or property damage—for example, a visitor trips over unsecured cable or drilling causes a leak. Covered defence costs may also be included, subject to the wording.
When comparing cctv installer public liability insurance, look beyond the schedule limit. Check the business description, height work, underground services, subcontractors, products and completed operations. Public liability insurance for security installers should reflect the actual mix of CCTV, alarms, intercoms, access control and maintenance.
Public liability is not a workmanship warranty. Rectifying the installer’s defective work may be excluded even when separate resulting damage is covered.
Professional Indemnity for CCTV Design and Advice
Professional indemnity insurance for cctv installers may be relevant when alleged negligence in design, specification, programming or advice causes financial loss. A client might say camera placement created a blind spot or storage capacity did not meet the brief.
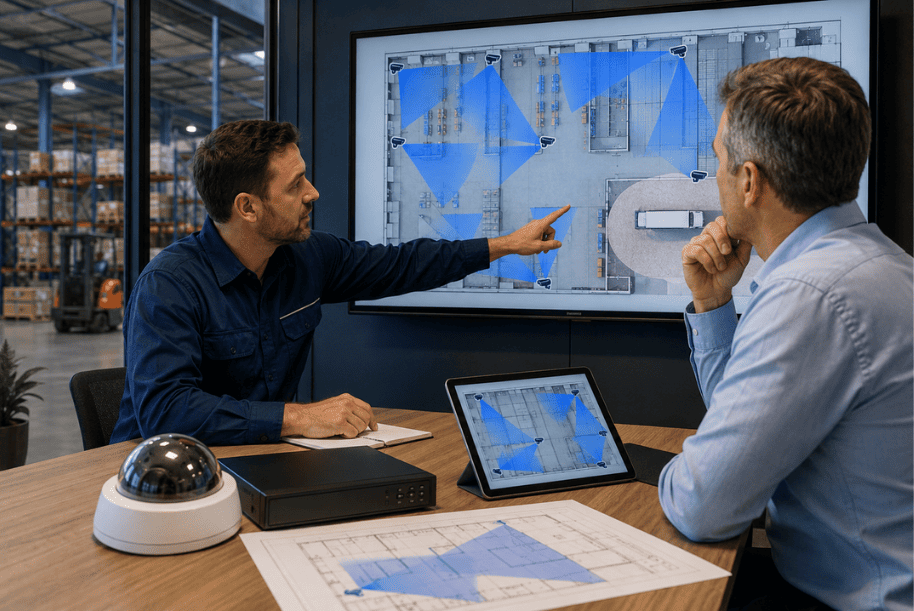
Recommending camera numbers, retention periods, network architecture or monitoring can amount to advice. Insurance for cctv system design advice should be considered where the client relies on those decisions. The same applies to professional indemnity insurance for security installers designing integrated alarm or access-control systems.
Business.gov.au says professional indemnity can help with legal action arising from professional advice or services. Response still depends on the defined services and allegations.
Faulty work, resulting damage and economic loss
Businesses often seek insurance for faulty security system installation after a dispute starts. The answer depends on the loss claimed.
If a loose camera falls onto a client’s vehicle, public liability may be relevant to resulting damage, while refitting the camera may be treated differently. If the system fails its agreed performance standard and the client seeks lost revenue, professional indemnity may be more relevant. Contractual liability, guarantees and known defects can change the outcome.
That is why does public liability cover faulty cctv installation and does insurance cover damage during cctv installation cannot be answered with a blanket yes. Separate the defective work, rectification, resulting damage and downstream loss, then test each against the wording.
Cyber, privacy and connected CCTV systems
Modern CCTV can involve cloud portals, mobile apps, administrator credentials, facial recognition and remote monitoring. A default password or misconfigured permission creates a different claim from a broken bracket.
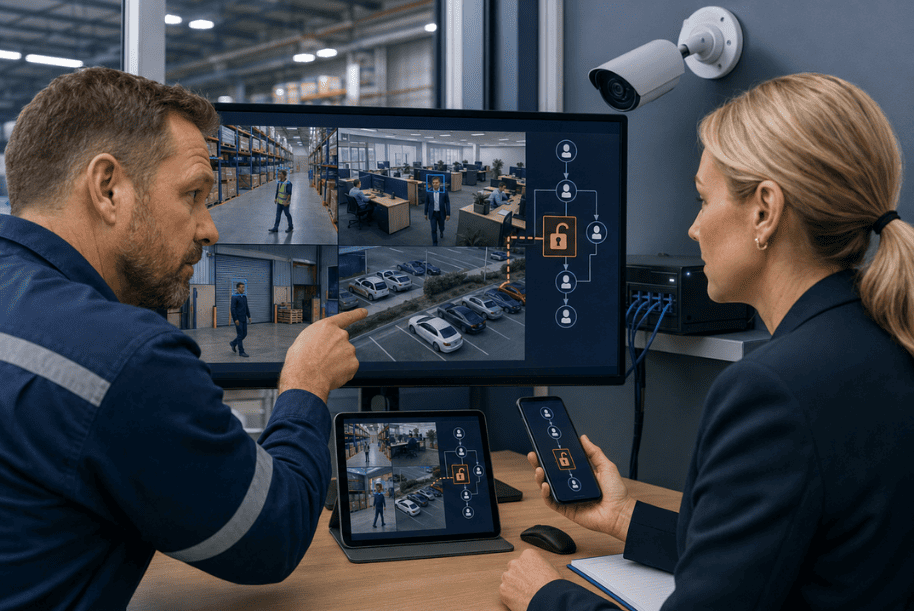
Cyber insurance for security system installers may help with incident response and certain third-party claims. Professional indemnity may also matter where negligent configuration or advice is alleged. Insurance for data breach caused by cctv installation should therefore be assessed across cyber and professional-liability wordings.
For entities covered by the Privacy Act, OAIC guidance says APP 11 requires reasonable steps to secure personal information. The Notifiable Data Breaches scheme may require notification where an eligible breach is likely to cause serious harm. Installers and clients should allocate control of recordings, credentials, retention and incident escalation.
Cover for CCTV tools and equipment
Liability insurance does not usually insure the installer’s own gear. Tools insurance for cctv installers or equipment insurance for cctv installers may be needed for test devices, cameras awaiting installation, cable locators, laptops, drills, ladders and portable equipment.
Insurance for stolen CCTV installation tools should be checked for geographic limits, unattended-vehicle conditions, overnight storage, proof of ownership and replacement basis. Stock or client equipment in transit may need separate consideration.
Employees, vehicles, works and subcontractors
A complete program may also consider commercial vehicle insurance for cctv installers, personal accident insurance for cctv installers, workers compensation insurance for cctv installers and contract works insurance for cctv installers, depending on the state, workforce and job structure.
Insurance for cctv installation subcontractors needs particular attention. Do not assume subcontractors are automatically insured. Contracts should allocate responsibility and address evidence such as a cctv installer certificate of currency. A certificate confirms policy details at a point in time; it does not expand cover or guarantee a claim.
Insurance requirements for security installation contractors
There is no single answer to cctv installer public liability requirements Australia. Licences, contracts, head contractors and tenders may impose different conditions. Workers compensation obligations are state or territory based.
Licensing is separate from insurance. Victoria Police identifies security equipment installation and advice as private-security activities. NSW Police says a Class 2C licence covers selling, installing, maintaining, repairing and advising on electronic security equipment including CCTV and alarms. Verify every jurisdiction in which you operate.
Who can CCTV installer insurance cover?
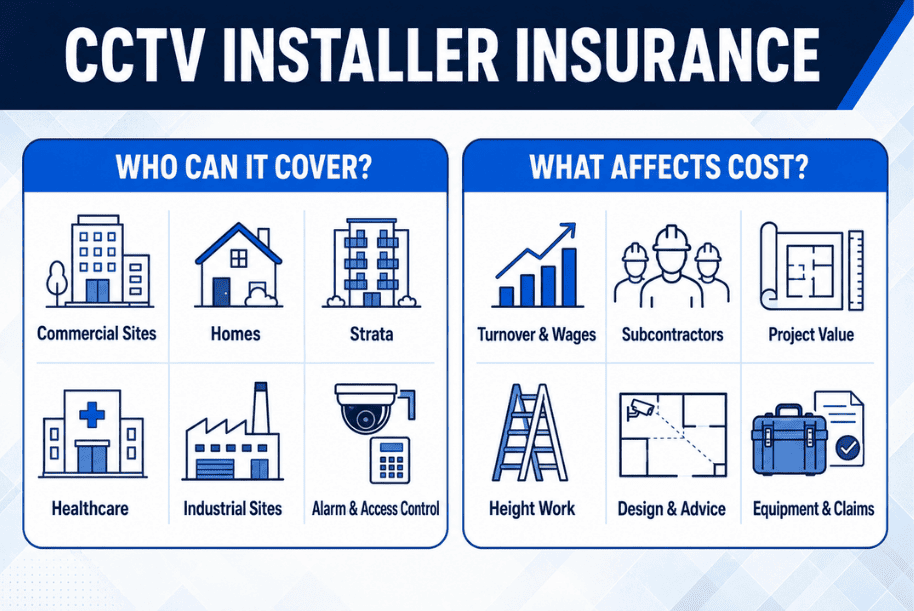
Insurance for commercial cctv installers may need to address warehouses, shops, offices, strata, healthcare or industrial sites. Insurance for domestic cctv installers involves occupied homes and different property-damage exposures. Alarm and cctv installer insurance may also need to include intercom and access-control activities.
Whether the need is described as security alarm and cctv installer insurance, security system installer insurance, surveillance system installer insurance or cctv contractor insurance, underwriting should follow the actual activities—not the label.
How Much Does CCTV Installer Insurance Cost?
CCTV installer insurance cost has no standard rate. Insurers may consider turnover, wages, subcontractor payments, project values, customers, height exposure, advice, equipment values, limits, excesses and claims history.
If asking how much does cctv installer insurance cost or how much is cctv installer insurance, start with accurate information rather than a price promise. Similar-sized installers can present very different risks if one fits domestic systems and another designs networked surveillance for hospitals. Price only matters when key activities and failure scenarios are addressed.
Questions to ask before the next installation
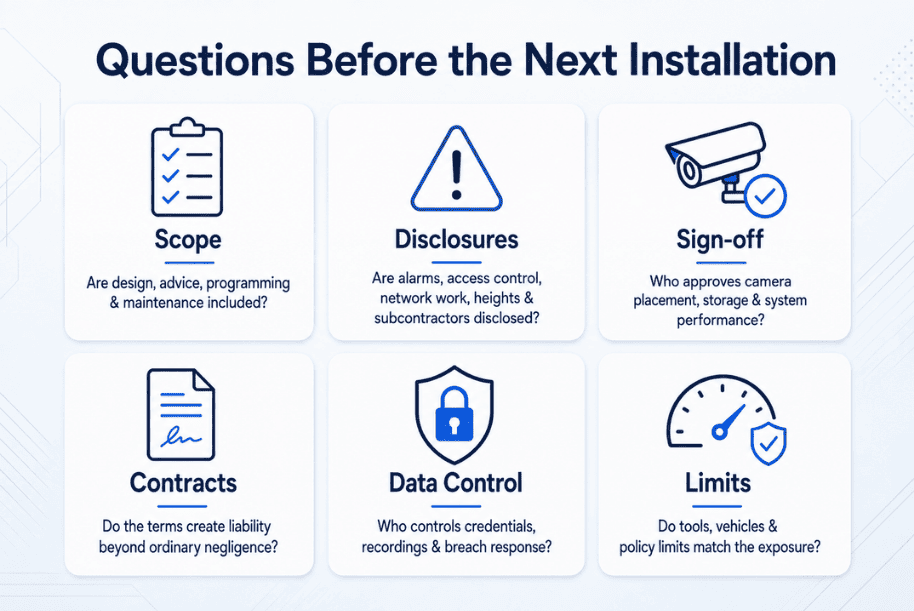
Before accepting a project or renewing cover, consider:
- Does the business description include design, advice, programming and maintenance?
- Are alarms, access control, network work, heights and subcontractors disclosed?
- Who signs off camera placement, storage and system performance?
- Does the contract create liabilities beyond ordinary negligence?
- Who controls credentials, recordings and breach response?
- Do tool, vehicle and policy limits match the exposure?
Frequently Asked Questions
Q1. Is CCTV installer insurance compulsory in Australia?
Ans 1. Not as one universal product. Licences, employment arrangements, contracts or sites may require particular cover or limits. Check state rules and each contract.
Q2. Do CCTV installers need public liability insurance?
Ans 2. It is commonly requested where work may injure someone or damage property. Whether it is legally or contractually required depends on the circumstances.
Q3. Do CCTV installers need professional indemnity insurance?
Ans 3. Consider it when an installer designs, specifies, recommends, configures or advises. The policy must recognise those services.
Q4. Does one policy cover every CCTV installation risk?
Ans 4. Usually not. Business insurance for cctv installers may coordinate several covers, each with its own triggers, exclusions, limits and conditions.
Speak to a broker who understands installation risk
When a system fails, “who pays?” depends on the contract, cause, allegations and policies—not a certificate label. GIS can review your activities, contracts, subcontractors and existing cover, then help structure cctv installer insurance Australia-wide.
GIS provides cctv installer insurance Melbourne contractors can tailor to their activities, backed by Australia-wide support. Call 1300 710 665 or request a review through our CCTV installer insurance page.
Important notice
This article is of a general nature only and does not take into account your specific objectives, financial situation or needs. It is also not financial advice, nor complete, so please discuss the full details with your insurance broker as to whether these types of insurance are appropriate for you. Deductibles, exclusions and limits apply. You should consider any relevant Target Market Determination and Product Disclosure Statement in deciding whether to buy or renew these types of insurance. Various insurers issue these types of insurance and cover can differ between insurers.
This article provides information rather than financial product or other advice. The content of this article, including any information contained in it, has been prepared without taking into account your objectives, financial situation or needs. You should consider the appropriateness of the information, taking these matters into account, before you act on any information. In particular, you should review the product disclosure statement for any product that the information relates to it before acquiring the product.
Information is current as at the date the article is written as specified within it but is subject to change. Global Insurance Solutions Pty Ltd make no representation as to the accuracy or completeness of the information. Various third parties have contributed to the production of this content. All information is subject to copyright and may not be reproduced without the prior written consent of Global Insurance Solutions Pty Ltd.

Risk Advisor, Insurance Broker & Director
With around 15 years in insurance, Yuvi Singh is a passionate Risk Advisor, Director, and Insurance Broker at Global Insurance Solutions. Backed by a Commerce degree and ANZIIF diploma, Yuvi leads a team servicing SMEs across industries like manufacturing, logistics, fuel, IT, and more. At GIS, clients benefit from tailored, transparent advice, access to 150+ insurers, and end-to-end risk solutions. Recognised as a 2022 Insurance Magazine Rising Star and 2024 Top Insurance Broker by Insurance Business Australia, Yuvi delivers flexible, effective outcomes with integrity and innovation.